
It all ADDS UP.
Discover more, every day.
Introducing SIB ADDS UP in partnership between Sharjah Islamic Bank and fitze, bringing together every day wellbeing, meaningful participation and rewarding experiences.
Whether it is a daily walk, a personal milestone or a new challenge, every action can add something to your day.
With SIB × fitze, enjoy access to activity tracking, challenges, rewards and exclusive benefits, with the Smart Health Ring connecting you to your wellbeing journey.
Not a Covered Card holder?
Your new Covered Card comes with more.
Apply for SIB Covered Card and spend AED 1,000 within 30 days of issuance to enjoy:
- A complimentary Smart Health Ring
- One-year complimentary fitze Pro membership
- 15 fitze Streaks annually
- Access to SIB Streaks and exclusive rewards
- Opportunities to earn cashback and enjoy partner benefits, subject to the programme terms
Existing SIB Covered Card Customers
There is more to enjoy with your SIB Covered Card.
As an existing SIB Covered Card customer, you can enjoy:
- A complimentary fitze Ring when you spend AED 10,000, or 25% discount on purchase of the Health Ring
- One year complimentary fitze Pro membership with the Health Ring
- 15 fitze Streaks annually
- Exclusive SIB Streaks and rewards
How It Works
- Apply for an SIB Covered Card or avail exclusive offer as an existing SIB Covered Cardholder.
- Meet the applicable spend target.
- Sign up on the fitze App and link your SIB Covered Card to unlock exclusive benefits.
- Track your fitness activity, participate in challenges and enjoy rewards.
Offer valid until 31st Jan 2027
Apply Now, SMS “Card” to 6667
For more information, call 600 SIB (742). Apply Now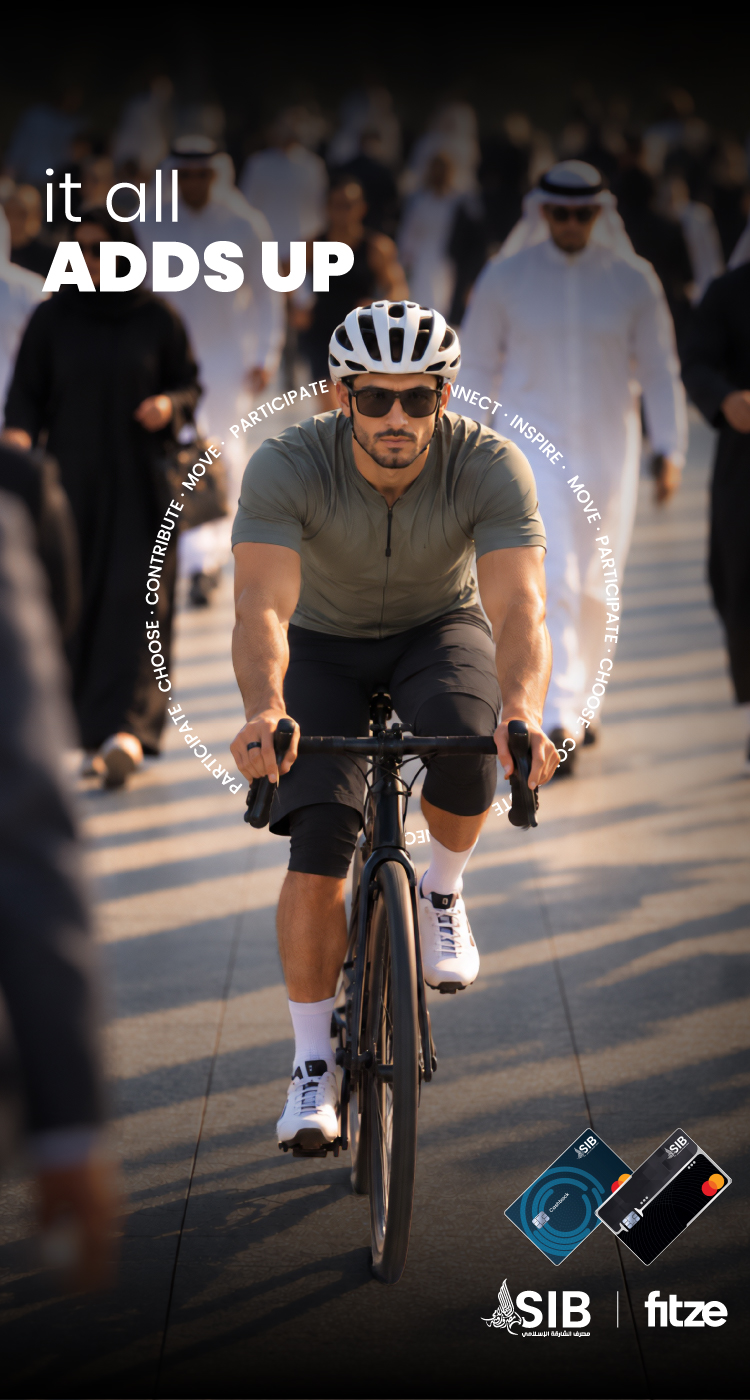
What would you like to do?

Give us feedback
Write to us and we will get back to you soon.

Apply Now
The online application takes only a few minutes to fill out.

Frequently asked questions
What is Islamic Home Finance?
Islamic Home Finance operates like a rent-to-own home purchase plan. The bank buys the property from the seller and leases it to the customer, with the agreement culminating in ownership at the end of the finance tenure.
How is Islamic Home Finance different from conventional mortgages?
In a conventional mortgage, the customer repays the loan with an added interest charged by the bank. In contrast, Islamic Home Finance adheres to sharia principles, where interest (riba) is prohibited. The bank purchases the property on the customer’s behalf and leases it to the customer, with rent determined for each lease renewal period.
What types of Islamic Home Finance does SIB provide?
SIB Islamic Home Finance is based on ijarah principles. Under this arrangement, the bank purchases the property and leases it to the customer for an agreed rent, which is subject to change during each lease renewal period.
Can non-Muslims apply for Islamic Home Finance?
Yes, SIB Home Finance is available to all customer segments, including individuals of any nationality and religion, whether salaried or self-employed.
What is the eligibility criteria for Islamic Home Finance?
Eligibility varies based on the customer’s profile. Visit SIB general terms & conditions for detailed eligibility information based on customer segments and property types.
What happens if I cannot make my payments?
Failure to make payments may result in:
Your account going into arrears, potentially affecting your credit rating and limiting future financing opportunities. Loss of your property, which may be repossessed by the bank.
Is takaful required for Islamic Home Finance?
Yes, both property and life takaful are mandatory for the duration of the finance and must remain valid until the finance is fully settled.
Can I settle my Home Finance early?
Yes, early settlement is permitted, subject to a fee as per the bank’s prevailing charges.
What types of properties are eligible for Islamic Home Finance?
SIB offers finance for:
Ready residential properties (villas, townhouses, or apartments)
Residential and non-residential land
Office spaces (serviced offices)
Retail spaces (shops or retail stores)
How is SIB Home Finance's profit rate applied?
SIB Home Finance is offered at a reducing profit rate.
Flat rate: the profit rate remains constant throughout the finance term and is calculated on the original principal amount.
Reducing rate: the profit is calculated on the outstanding balance, which decreases as settlement/repayments are made.
Reducing rates typically reflect the actual cost of finance more accurately than flat rates, even if the advertised flat rate appears lower.
How much deposit is required for Islamic Home Finance?
The deposit requirement depends on the customer’s nationality, property type, and value:
Residential property:
UAE nationals:
First house/owner occupier:
Property ≤ AED 5 million: minimum 15%
Property > AED 5 million: minimum 25%
Second/subsequent houses or investment property: minimum 35%
Expatriates:
First house/owner occupier:
Property ≤ AED 5 million: minimum 20%
Property > AED 5 million: minimum 30%
Second/subsequent houses or investment property: minimum 40%
Non-residential property:
New purchase:
UAE nationals: up to 35%
Expatriates: up to 40%
Equity release (ready non-residential property):
UAE nationals: up to 40%
Expatriates: up to 45%
Equity release (non-residential land):
All nationalities: up to 50%





 For an optimal experience, please